The Ultimate Home Insurance Quote Checklist
Get a home insurance quote for high-risk properties with practical tips on documentation, finding the right insurer, and preparing for a smooth application.
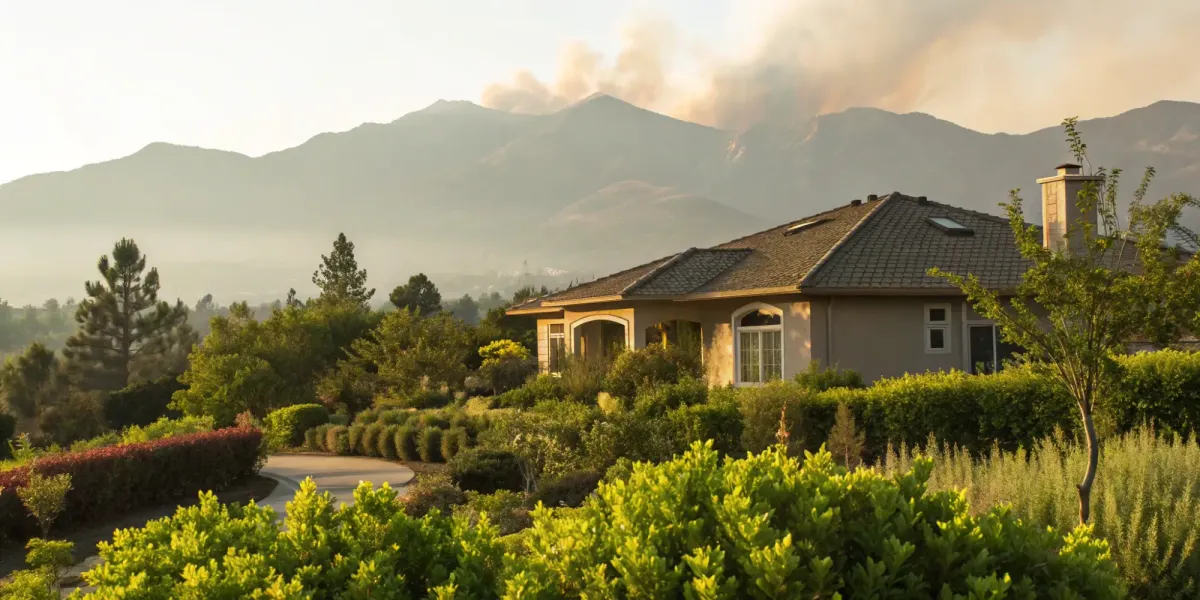
You’ve done all the right things. You cleared brush for defensible space, installed ember-resistant vents, and maybe even put on a fire-rated roof. So why does it feel like none of that matters when you ask for a home insurance quote? Your hard work is your greatest asset, but you have to know how to show it. Insurers often just see a location on a map; it's your job to give them the full picture. This guide provides a simple plan for documenting your upgrades and finding providers who recognize and reward your proactive work.
Key Takeaways
- Build your home's resume: Before seeking quotes, compile a detailed list of your property's features, recent upgrades (like a new roof), and any fire mitigation efforts you've completed. This documentation proves you're a proactive homeowner and helps agents find you the most accurate and favorable rates.
- Look beyond mainstream insurers: If you're getting denied by big-name companies, connect with an independent insurance agent. They have access to specialty carriers that focus on high-risk properties and can shop the market on your behalf to find a policy that fits your needs.
- Compare quotes by coverage, not just cost: The cheapest option isn't always the right one. Line up your quotes and look closely at the dwelling coverage limits, policy exclusions, and deductibles. A slightly higher premium might offer significantly better protection and a lower out-of-pocket cost when you need it most.
Understanding the Average Cost of Homeowners Insurance
Before you start comparing quotes, it helps to have a baseline understanding of what homeowners insurance costs. But let’s be clear: national averages are just a starting point. If you live in a high-risk area, your reality will likely look very different. Think of these numbers as a reference point, not a rule. Your premium is a unique reflection of your home’s specific location, value, and features. Knowing the general landscape helps you see where you fit in and why working with an agent who understands your specific risks is so important for finding a fair price.
National and State Averages
Across the United States, the average homeowner pays around $1,966 per year, or about $163 per month, for a new policy. While this figure gives you a general idea, it’s heavily skewed by lower-risk states. In places like California, where wildfire risk is a major factor, premiums are often significantly higher. This is because insurance pricing is all about risk assessment. When the potential for widespread, costly claims goes up, so do the rates for everyone in that area. It’s why a national average can feel a bit misleading when you’re getting quotes that are two or three times that amount.
How Coverage Amount Affects Your Premium
One of the biggest factors driving your premium is your dwelling coverage limit—the amount it would cost to completely rebuild your home from the ground up. The more coverage you need, the more you can expect to pay. For instance, a policy with $200,000 to $299,999 in dwelling coverage costs about $1,679 annually on average. If you need to insure a home for $800,000 to $899,999, that average premium jumps to over $3,000. This makes sense; the insurer is taking on more financial risk with a higher-value property, and the premium reflects that increased responsibility.
Cost for a $400,000 Home
So, what does this look like for a specific home value? On average, you can expect to pay between $1,500 and $2,500 per year for a $400,000 house. However, this range is where location becomes critical. A $400,000 home in a low-risk suburb will be on the lower end of that scale, while the same value home in a high-risk fire zone could easily exceed it. This is why simply looking at your home's value isn't enough to predict your insurance cost accurately.
Comparing Costs Between Insurance Companies
You’ll often see articles listing the cheapest homeowners insurance companies, with names like USAA and Auto-Owners frequently at the top. While they may offer great rates in some parts of the country, these standard carriers often won't even provide a quote for properties in high-risk zones. This is a common point of frustration for homeowners in areas like the California foothills. Instead of spinning your wheels with companies that aren’t equipped to handle your risk, your time is better spent working with an independent agent. We specialize in connecting homeowners like you with specialty carriers who understand and are willing to insure properties in catastrophe-prone regions.
What Makes a Home "High-Risk"?
When an insurance company uses the term "high-risk," it isn't a judgment about you or how you care for your home. It’s simply a classification based on data that suggests your property has a higher-than-average chance of a future claim. Insurers look at a combination of factors—some you can control and some you can't—to determine this risk level. Understanding what they’re looking for is the first step toward finding fair and reliable coverage.
Think of it as an equation. Your location, your home’s specific features, and your claims history are all variables that add up to your final risk score. For homeowners in California, location often weighs heavily, but it's never the only piece of the puzzle. By breaking down each component, you can get a clearer picture of how an insurer sees your home and identify areas where you might be able to improve your property’s profile. Let's walk through the key factors that contribute to a high-risk designation.
Does Your Neighborhood Increase Your Risk?
Your home's address is one of the most significant factors in determining your insurance risk. If you live in an area prone to natural disasters, insurers will take note. For those of us in California, this often means proximity to areas with a history of wildfires. Insurance companies use advanced mapping tools, like Fire Hazard Severity Zone maps, to assess the likelihood of events like fires, floods, or earthquakes impacting your property. Living in a designated high-risk zone doesn't automatically make you uninsurable, but it does mean that carriers will look more closely at your home's ability to withstand a potential disaster.
Property Features That Raise Red Flags
Beyond your location, the specific characteristics of your home play a huge role. An older roof that hasn't been replaced in decades is seen as a higher risk for wind or water damage compared to a brand-new one. Features that increase liability risk, like a swimming pool, hot tub, or trampoline, can also place your home in a higher-risk category due to the potential for accidents. Even the age of your home’s core systems, such as its plumbing and electrical wiring, can be a factor. Insurers are looking for any feature that might increase the odds of a claim, so taking steps toward hardening your home can make a real difference.
Attractive Nuisances: Pools, Trampolines, and More
In the insurance world, things like swimming pools, trampolines, and even elaborate treehouses are known as attractive nuisances. It’s a formal term for something on your property that could attract a child and pose a danger. While you see a fun backyard, an insurer sees a potential liability claim waiting to happen. The risk of an accident, especially involving a guest or a neighbor’s child, is why these features can make it harder or more expensive to secure a policy. But having a pool doesn't mean you're out of options. Taking clear safety precautions, like installing a four-sided fence with a self-latching gate around your pool or adding a safety net to your trampoline, demonstrates that you're actively managing the risk. These steps can make a significant difference when an underwriter reviews your application.
Will Past Insurance Claims Affect Your Quote?
Your personal claims history follows you, not just your property. If you've filed multiple homeowners insurance claims in the past few years, an insurer might see you as a higher risk, even if the claims were for different properties. This is because a pattern of claims can suggest underlying issues or simply bad luck that a carrier may not want to take on. It’s not personal; it’s statistical. Insurers access this information through a database called a CLUE report, which provides a history of property claims. A clean record can go a long way, while a busy one may lead to higher premiums or fewer coverage options.
Are These Safety Gaps Making Your Home High-Risk?
Finally, insurers assess your home for basic safety and security measures. A home without modern smoke detectors, a fire extinguisher, or a security system may be considered a higher risk for fire or theft. The construction materials used in your home also matter—for example, a wood-shake roof is a much greater fire risk than a tile or metal one. Even having a large, dead tree looming over your house can be a red flag. These are often seen as preventable risks, and addressing them not only makes your home safer for your family but can also make it more attractive to insurance providers.
How Personal Factors Can Influence Your Rate
While your home’s location and features are the main event, certain personal details also play a supporting role in shaping your insurance premium. Insurers look at these factors to build a more complete picture of risk. It’s not about judging your lifestyle; it’s about using broad statistical data to predict the likelihood of a future claim. Understanding these elements can help you see your policy from the insurer's perspective and demystify why your rate is what it is.
The Role of Your Credit Score
In many states, including California, insurance companies may use a credit-based insurance score to help determine your premium. This isn't the same as the score a lender sees, but it's derived from similar information in your credit report. The logic behind this practice is that industry data shows a correlation between how a person manages their financial responsibilities and their likelihood of filing a claim. A stronger credit-based insurance score can often lead to lower homeowners insurance rates, as it suggests a lower risk profile to the carrier.
Other Factors Like Marital Status
Other personal details can also subtly influence your rates. For example, some insurers offer slightly better rates to married couples. This isn't arbitrary; it's based on historical data suggesting that married homeowners tend to file fewer claims than single homeowners. Similarly, having a mortgage can sometimes be viewed favorably, as it ensures that you will maintain continuous insurance coverage to protect the lender's investment—and your own. While these factors are typically less impactful than your home's location or condition, they contribute to the overall calculation.
Common Reasons Your Rates Might Increase
It’s one of the most frustrating experiences as a homeowner: you open your renewal notice to find your premium has jumped, seemingly without reason. While it can feel random, there are usually specific drivers behind a rate increase. Some are tied to your personal history, while others are connected to broader economic trends that affect the entire insurance market. Knowing what causes these changes can help you anticipate them and have a more productive conversation with your agent about your options.
If you’ve filed several claims in recent years, an insurer may view your property as having a higher probability of future losses, leading to a higher premium at renewal. Likewise, if you let your previous policy expire and had a gap in coverage, a new carrier might charge more to take on what they see as an unknown risk. An insurer may also increase your rate after an inspection reveals that your home needs significant repairs, such as a new roof or updated electrical systems, as these issues present a greater chance of a future claim.
Sometimes, a rate increase has nothing to do with you or your home specifically. When the costs of construction materials and labor rise, the amount it would take to rebuild your home also goes up. This is known as inflation. To ensure you have enough coverage to fully replace your home after a disaster, your policy's dwelling limit must increase, which in turn raises your premium. This is a widespread issue that reflects the current cost of rebuilding and affects homeowners across the board, especially in high-cost states like California.
Your Pre-Quote Checklist: How to Prepare
Getting an insurance quote when you live in a high-risk area can feel daunting, but a little preparation goes a long way. Walking into the process with your information organized not only makes things smoother but also helps you present your home in the best possible light. Think of it as building a case for why your property is a good risk, despite its location. When you provide clear, detailed information, you help an agent understand the full picture of your home—including all the steps you’ve taken to make it safer. This proactive approach can make a real difference in the options available to you. By having everything ready, you empower your agent to find the most accurate and competitive quotes. Let’s walk through the exact steps to get you prepared.
Get Your Paperwork in Order
First things first, let's get your paperwork in order. Having your documents ready from the start saves you from scrambling for them later. You’ll want to pull out your current homeowners insurance policy, specifically the declarations page, which summarizes your coverage. Also, grab any recent mortgage statements and property appraisals. If you’ve had professional inspections or have documentation of recent upgrades (like a new roof or updated electrical system), get those ready, too. This information is the foundation of your quote, giving an agent the details they need to provide financial protection for your home and belongings. It’s the first step to showing you’re an organized and proactive homeowner.
Build a "Home Resume" for Insurers
Next, create a one-page summary of your home’s key features. This isn't just for your agent; it's a helpful reference for you, too. List specifics like the year your home was built, its total square footage, and the type of construction. Be sure to include the age and material of your roof, as well as the last time your plumbing, electrical, and HVAC systems were updated. An insurance provider will often send someone to verify your home’s condition and calculate its rebuilding cost, so having accurate information upfront is key. This sheet ensures you provide consistent details across different applications and helps you remember all the important features that make your home unique and insurable.
Do a Quick Home Safety Audit
Now for the part that can directly impact your premium: your home’s safety and security features. Make a detailed list of every protective measure you have in place. This includes standard items like smoke detectors, fire extinguishers, and deadbolt locks. Also, be sure to list any advanced security systems, especially if they are centrally monitored for fire and burglary. For those of us in wildfire-prone areas, this is where you highlight mitigation efforts. Note things like ember-resistant vents, a Class A fire-rated roof, or defensible space clearance. These features demonstrate that you’re actively working to reduce risk, which can lead to valuable discounts and make your application more attractive to insurers.
How to Get a Copy of Your Claims History
Finally, it’s wise to know what your insurance history looks like from a provider’s perspective. Insurance companies will review your past claims to gauge your risk profile, and a history of frequent claims can lead to higher rates or even make it difficult to find coverage. You can request a copy of your CLUE (Comprehensive Loss Underwriting Exchange) report, which details any property claims you’ve filed over the last seven years. Review it carefully for accuracy. If you find any errors, you can dispute them. Going into the quote process with a clear understanding of your claims history means there won’t be any surprises, and you’ll be prepared to discuss it if needed.
Where to Find High-Risk Home Insurance
Finding the right insurance for a home in a high-risk area can feel like a scavenger hunt where the map is missing. You might hear "no" more often than you'd like, or see quotes that make your jaw drop. But don't get discouraged. The right coverage is out there—you just need to know where to look. The key is to move beyond the big-name insurers you see on TV and explore channels that specialize in properties just like yours.
Think of this as a strategic search, not a desperate one. Your goal is to find an insurance partner who understands the unique risks of your location, whether it's wildfires, flooding, or something else. This means connecting with professionals who have access to different markets and understanding all your options, from specialty private insurers to state-run programs. With the right approach, you can find a policy that protects your home and gives you peace of mind without breaking the bank. It’s all about having a clear strategy and knowing who can help you execute it.
Why an Independent Agent Can Help
If you’ve only ever worked with a single insurance company, the idea of an independent agent might be new to you. Unlike captive agents who represent one company, an independent insurance agent works with multiple carriers. This is a huge advantage when you have a high-risk home. They have access to specialty insurers that don’t sell directly to the public and can shop around on your behalf to find the best coverage and rates. They understand the nuances of the high-risk market and can help you present your home in the best possible light, increasing your chances of getting a great policy.
Finding a Specialty Insurer
Not all insurance companies are pulling out of high-risk areas. Some are actually leaning in, creating policies specifically for homes with higher exposure to risks like wildfires. These specialty insurers often use more advanced technology and data to accurately assess a property’s individual risk, rather than just looking at its ZIP code. They might consider your home’s specific building materials or the defensible space you’ve created. Finding these carriers can be tough on your own, which is another reason why working with an independent agent who has established relationships with them is so valuable.
What Is a FAIR Plan (And Is It for You?)
If you’ve exhausted your options in the private market, your state’s FAIR Plan might be your next step. FAIR (Fair Access to Insurance Requirements) Plans are state-mandated programs that act as an insurer of last resort for high-risk properties. For homeowners in wildfire-prone areas, the California FAIR Plan is a common option. It’s important to know that these policies often provide very basic coverage, sometimes only for fire damage. You’ll likely need to purchase a separate "difference in conditions" policy to cover other perils like theft and liability. It’s a safety net, but be sure you understand exactly what it does and doesn’t cover.
Smart Ways to Research Insurers Online
Even when you’re working with an agent, it’s smart to do your own homework. Once you have a few potential insurers, look them up online. Read customer reviews to get a sense of their claims process and service. You should also check their financial strength rating from a reputable source like AM Best, which indicates their ability to pay out claims. Finally, comparing home insurance quotes is essential. This helps you see how different companies weigh your risk factors and ensures you’re getting the best possible value for the coverage you need. A little research can give you confidence that you’re choosing a reliable, long-term partner.
What Does a High-Risk Policy Actually Cover?
Once the quotes start rolling in, it’s tempting to just look at the price tag. But the real value of an insurance policy is in the details. Understanding what’s covered—and what isn’t—is the most important step in choosing the right protection for your home. Think of your policy as a financial safety net. You want to be sure it’s strong enough to catch you and doesn’t have any unexpected holes.
This is where you get to be your own best advocate. By learning the language of insurance and looking closely at the coverage options, you can compare policies accurately and make a choice that lets you sleep soundly at night. Let’s walk through the key components of a homeowners policy so you know exactly what to look for.
What Standard Policies Cover
At its core, homeowners insurance offers financial protection if your house or personal belongings are damaged or destroyed by a covered event. A standard policy typically covers common risks like fire and smoke, theft, windstorms, hail, and water damage from internal sources like a burst pipe or a faulty appliance. It also includes liability coverage, which is crucial if someone is accidentally injured on your property. This part of the policy can help pay for their medical bills or legal fees if you’re found responsible. It’s the foundational coverage that every homeowner needs.
Typical Limits for Personal Property and Liability
Beyond the structure of your house, your policy protects your personal belongings—everything from your sofa to your spoons. Insurers typically set your personal property limit as a percentage of your dwelling coverage, usually between 50% and 70%. So, if your home is insured for $500,000, you might have $250,000 to $350,000 for your stuff. While that sounds like a lot, it's crucial to do a quick mental inventory. Would that amount truly cover the cost of replacing everything you own after a total loss? It's also important to know that standard policies place lower limits on high-value items like jewelry, art, and collectibles. If you have special items, you may need to add extra coverage to make sure they're fully protected.
Personal liability coverage is your financial backstop if someone is injured on your property and you're found legally responsible. Most standard policies start with a minimum of $100,000 in coverage, but that's rarely enough to protect your assets. A good rule of thumb is to choose a limit of liability that is at least equal to your net worth. Tally up your assets—your home equity, savings, investments—and make sure your coverage meets or exceeds that number. If you have $400,000 in assets, you should aim for at least that much in liability protection. This ensures that a lawsuit won't jeopardize the financial future you've worked so hard to build.
Do You Need Extra Coverage?
For those of us in high-risk areas, a standard policy is often just the starting point. It’s critical to know that most basic policies do not cover damage from floods or earthquakes. These events require separate policies or specific add-ons, often called endorsements. Given that floods can happen in any state, it’s an important piece of extra coverage to consider. If you live in a wildfire-prone area, you’ll also want to confirm your fire coverage is robust and doesn't have special limitations. Don’t assume you’re covered for every possibility; ask specifically about the risks relevant to your location.
Dwelling Coverage: Rebuild Cost vs. Market Value
This is one of the most common points of confusion, so let’s clear it up. The "dwelling coverage" amount on your policy is not based on your home's market value—what you could sell it for. Instead, it’s based on the estimated cost to rebuild your home from the ground up if it were completely destroyed. This figure includes materials, labor, and permits, but it completely ignores the value of your land. Your home could have a market value of $800,000 because it’s in a desirable neighborhood, but the actual cost to rebuild the structure might only be $500,000. That $500,000 is the number your insurance focuses on. Getting this number right is the single most important part of your policy.
The 80% Rule Explained
You might hear agents talk about the "80% rule," and it’s a big deal. Most insurance companies require you to insure your home for at least 80% of its total replacement cost. If your coverage drops below this threshold, you could face a penalty when you file a claim. For example, if your home’s replacement cost is $500,000, you need at least $400,000 in dwelling coverage to satisfy the rule. If you only have $300,000 and suffer a partial loss, the insurer might not pay the full cost of the repair, leaving you to cover a larger portion out-of-pocket. It’s their way of ensuring homeowners maintain adequate coverage and share in the risk if they don't.
Why You Should Consider Insuring for More Than 100%
While insuring for 100% of your home's estimated replacement cost seems logical, it might not be enough, especially after a widespread disaster like a wildfire. When an entire community needs to rebuild at the same time, the demand for materials and skilled labor skyrockets, driving up costs significantly. This is often called "demand surge." On top of that, local building codes may have been updated since your home was built, requiring more expensive materials or construction methods. To protect against these variables, consider adding an "extended replacement cost" endorsement to your policy. This provides an extra cushion, often 25% to 50% above your dwelling limit, ensuring you have the funds to rebuild, no matter what.
Common Exclusions to Watch For
Every insurance policy has two important sections you need to read carefully: exclusions and limitations. Exclusions are the specific events or types of damage that the policy will not pay for. For example, damage from neglect or general wear and tear is almost always excluded. Limitations are the maximum amounts the insurer will pay for certain types of claims. Your policy might cover stolen jewelry, for instance, but only up to a limit of $1,500. If your collection is worth more, you’ll need an endorsement to cover its full value. Knowing these boundaries upfront prevents major disappointments during a claim.
Coverage Gaps for Floods, Earthquakes, and More
It's a costly mistake to assume your standard homeowners policy covers every type of disaster. The two biggest gaps you'll find are almost always flood and earthquake damage, as most policies explicitly exclude them. For those of us in California, this isn't a minor detail—it's a critical vulnerability. To properly protect your home, you'll need to purchase separate coverage. Flood insurance is often available through the National Flood Insurance Program (NFIP), which can also cover mudflows, while earthquake coverage is typically sold as a standalone policy. Understanding these exclusions now prevents major surprises later and is the first step toward building a truly comprehensive protection plan.
How to Choose Your Deductible
Your deductible is the amount of money you agree to pay out-of-pocket before your insurance coverage kicks in. Think of it as your share of the repair cost. Choosing a higher deductible usually results in a lower monthly or annual premium, which can be tempting. However, it’s important to be realistic. Make sure you select a deductible that you could comfortably afford to pay on short notice. If a $5,000 deductible would strain your finances, it might be better to choose a lower one, even if it means a slightly higher premium. It’s all about finding the right balance for your budget.
Other Types of Property Insurance
While we've focused on insurance for a single-family home, property protection isn't one-size-fits-all. Your insurance needs change depending on whether you own a condo, rent an apartment, or are a landlord for an investment property. Each situation requires a specific type of policy designed to cover the unique risks involved. Understanding these differences is key to making sure you have the right coverage, no matter what kind of property you call home or manage. It ensures that you aren't paying for coverage you don't need, while also preventing dangerous gaps in your financial safety net. Let's look at the main options.
Policies for Condos, Renters, and Landlords
If you own a condo, your needs are different from a traditional homeowner. Your condo association has a master policy that covers the building's exterior and common areas, but you're responsible for everything inside your own walls. That's where condo insurance, often called an HO-6 policy, comes in. It protects your personal belongings, interior structures like cabinets and flooring, and provides liability coverage if someone is injured in your unit. This policy works alongside the master policy to give you comprehensive protection without overlapping coverage.
Don't make the mistake of thinking your landlord's insurance covers your personal items—it doesn't. Renters insurance is an affordable and essential policy that protects your belongings from events like fire or theft. It also includes liability coverage, which can be a lifesaver if a guest is injured in your apartment and you're found responsible. As financial experts often point out, it's a smart choice for anyone who rents, providing significant peace of mind for a relatively low cost. It ensures your personal assets are protected, even if you don't own the building you live in.
If you own a property that you rent out to others, you need a specialized policy to protect your investment. Landlord insurance is designed specifically for this purpose. It typically covers the physical structure of the building, provides liability protection in case a tenant or visitor is injured on the property, and can even cover your loss of rental income if the home becomes uninhabitable due to a covered event like a fire. This policy is crucial for managing the financial risks that come with being a property owner.
Smart Questions to Ask Every Insurance Provider
Getting an insurance quote isn’t a one-way interview where you’re the only one being evaluated. It’s your chance to interview the insurance provider, too. Asking the right questions now can save you from major headaches and financial surprises down the road. Before you commit to a policy, make sure you have a clear conversation with the agent or representative. Use this time to get a feel for their customer service and to confirm you’re getting the right protection for your home.
"What Are My Exact Coverage Limits?"
When you’re comparing quotes, you need to be sure you’re comparing apples to apples. A lower price might look tempting, but it could mean you’re getting significantly less coverage. Ask for a detailed breakdown of the policy’s limits. Specifically, you’ll want to know the coverage amounts for your dwelling (the structure of your home), other structures (like a garage or shed), personal property, and liability. Don’t be afraid to ask about what’s not covered. For homes in high-risk areas, it’s critical to understand any specific exclusions or limitations related to wildfires, floods, or earthquakes.
"What's Your Claims Process Like?"
In a perfect world, you’d never have to file a claim. But preparing for the worst is what insurance is all about. A smooth and supportive claims process is just as important as a good premium. Ask for a step-by-step explanation of how to file a claim. Who is your first point of contact? What is the typical timeline for an inspector to visit and for you to receive payment? Understanding their process ahead of time helps you gauge how responsive and organized the company is. This is the moment you’ll need your insurer the most, so make sure you’re choosing a partner you can count on.
"What Are My Payment Options?"
Let’s talk money. Two key terms you need to be crystal clear on are your premium and your deductible. Your premium is the regular payment you make to keep your policy active. Your deductible is the amount you have to pay out-of-pocket on a claim before the insurance company starts paying. Generally, a higher deductible leads to a lower premium, and vice versa. Ask the agent to show you quotes with a few different deductible options so you can see how it impacts your premium. Choose a deductible that you could comfortably pay tomorrow without causing financial strain.
"How Exactly Did You Calculate My Risk?"
Transparency is key. Asking an insurer how they arrived at your quote can give you valuable insight into how they view your property. Insurance companies calculate your risk based on many factors, including your home’s location, its age and construction type, your claims history, and the cost to rebuild it. By understanding what they see as your biggest risks, you can have a more productive conversation. This question also opens the door to ask, "What specific actions can I take to lower my premium?" This could lead to discounts for fire mitigation efforts or security system installations.
Getting Your Home Insurance Quote: What to Expect
Once you’ve gathered your documents and identified potential insurers, it’s time to start requesting quotes. This part of the process can feel a bit like a black box, especially when you own a home that carriers consider high-risk. You might find that instant online quotes aren’t always available, and the process often requires more documentation and a few conversations. But don’t let that discourage you. Being prepared and knowing what’s coming will help you feel in control and find the best possible policy for your home.
Think of the quote process not as a test, but as a conversation. You’re providing a detailed picture of your property, and the insurer is calculating the financial risk of protecting it. For high-risk homes, this calculation is more complex. Underwriters will look at everything from your roof material and defensible space to your proximity to fire hydrants and your claims history. The goal is to get a few solid quotes from different carriers so you can make an informed decision. We recommend getting quotes from at least three different insurance companies to give yourself a clear view of your options. This helps you understand the market rate and identify which insurer offers the most value for your specific situation.
Your Step-by-Step Application Guide
The first step is filling out an application. You can often start this online by getting a free quote, which will ask for basic information like your name, address, and the age of your home. For a high-risk property, this initial form is usually just the beginning. An agent or underwriter will likely follow up to ask for more details and the documents you’ve already prepared, like your property information sheet and any inspection reports. Be ready to answer specific questions about your home’s construction, updates you’ve made, and any fire mitigation efforts you’ve undertaken. It’s crucial to be thorough and honest here, as any inaccuracies could lead to problems with a future claim.
How Long Does It Take to Get a Quote?
While some standard home insurance quotes can be generated in minutes, getting a quote for a high-risk property often takes longer. Insurers need time to perform their due diligence, which can involve reviewing wildfire risk models, satellite imagery, and third-party inspection reports. This detailed underwriting process can take anywhere from a few days to a couple of weeks. Don’t be alarmed by the wait; it’s a sign that the insurer is taking a serious look at your home’s unique characteristics. Use this time to continue gathering quotes from other carriers. Patience is key to ensuring you don’t rush into a policy that isn’t the right fit.
How to Compare Your Quotes Fairly
When the quotes start rolling in, it’s tempting to just look at the annual premium and pick the cheapest one. However, you need to make sure you're comparing policies that offer similar protection. Create a simple chart to compare the key elements of each quote side-by-side. Look closely at the coverage types and limits for your dwelling, personal property, and liability. Pay special attention to the deductibles—both the standard deductible and any separate ones for perils like wildfires or hurricanes. A policy with a lower premium might have a much higher deductible, meaning you’d pay more out-of-pocket if you ever had to file a claim.
Watch Out for These Red Flags
As you compare quotes, keep an eye out for potential red flags. Be wary of any quote that is dramatically lower than all the others, as it could signal insufficient coverage or hidden exclusions. Some policies for high-risk homes might include special rules, like excluding coverage for cosmetic damage from wind or hail. If you've made claims before, you might notice your rates are higher, which is standard. However, you should also check the insurer's reputation and financial stability. You can look up an insurer’s rating through independent agencies like AM Best to ensure they have a strong track record of paying claims. A reliable insurer will be transparent and happy to answer all your questions.
How to Lower Your Insurance Premium
Seeing a high insurance quote can be discouraging, but it doesn’t have to be the final word. While living in a high-risk area means you’ll likely face higher costs, you have more control over your premium than you might think. Insurance companies base their prices on risk—the lower your property’s perceived risk, the lower your premium can be. By taking proactive steps to make your home safer and demonstrating your commitment to maintenance, you can directly influence how insurers calculate your rate. It’s about showing them that you’re a responsible partner in protecting your property.
Simple Upgrades to Make Your Home Safer
One of the most effective ways to lower your premium is to reduce your home’s vulnerability to damage. For homeowners in wildfire-prone areas, this means focusing on home hardening. Simple actions like installing ember-resistant vents and clearing flammable vegetation to create defensible space can make a significant difference. Larger projects, such as upgrading to a Class A fire-rated roof or installing a residential sprinkler system, are major investments that can lead to substantial premium reductions. Even installing storm shutters or impact-resistant windows to protect against wind can improve your risk profile. Think of these upgrades not just as expenses, but as investments in your home’s safety and your financial peace of mind.
Prove Your Home Is Less Risky with Documentation
When an insurer assesses your property, they’re trying to get an accurate picture of its condition and replacement cost. Don’t let them guess. You can help the process and ensure you get credit for your hard work by providing thorough documentation. Keep a file with receipts and contracts for any major upgrades, like a new roof, updated electrical system, or new plumbing. Take before-and-after photos of projects, such as clearing brush or installing a new fence. An organized home inventory and a summary of recent improvements can show an underwriter that your home is well-maintained and less risky than a comparable property, potentially leading to a better rate.
Don't Miss Out on These Discounts
Insurance companies offer a wide range of discounts, but they aren’t always applied automatically. It’s up to you to ask your agent what you might qualify for. The most common discount comes from bundling your home and auto policies with the same carrier. You may also be eligible for savings if you have a home security system, smoke detectors, or a new roof. Some insurers offer discounts for being claims-free for a certain number of years, for living in a gated community, or even based on your age. Make a list and ask your agent to review every possible discount with you—you might be surprised by how much you can save.
Bundling Home and Auto Insurance
If you’re looking for the single biggest discount, this is almost always it. Combining your home and auto insurance policies with the same company, a practice known as bundling, can lead to substantial savings. It’s a simple strategy that insurers use to reward customer loyalty, and the financial benefit can be significant. For instance, Progressive reports that customers who bundle their home and auto policies save over $1,000 on average. Beyond the savings, it also simplifies your life by letting you manage both policies with one provider. When you’re getting quotes, always ask the agent to show you the price both as a standalone policy and as a bundle—the difference might be all you need to see.
Other Discounts for New Homes, Loyalty, and Paying in Full
Bundling is just the beginning. Insurers offer a whole menu of other discounts that can chip away at your premium, but you often have to ask for them. You may qualify for savings if your home was recently built or has had major systems updated. Protective devices, like centrally monitored security systems, smoke detectors, and even fire extinguishers, can also earn you a discount. Don't forget about policy-related savings, either. Many companies will lower your rate if you pay your entire annual premium upfront, remain a loyal customer for several years, or enroll in paperless billing. Be proactive and ask your agent to review every possible discount with you to make sure you’re not leaving any money on the table.
Highlight Steps You've Taken to Reduce Risk
Beyond major upgrades, consistent maintenance shows an insurer that you’re a responsible homeowner. Before an inspection, walk around your property and address any potential issues. Repair cracked walkways, secure loose railings, and trim overhanging tree branches. Clear any debris from your yard and gutters. Inside, make sure your electrical, plumbing, and heating systems are in good working order and up to code. Documenting these routine maintenance tasks can also be helpful. By presenting a well-cared-for home, you demonstrate that you’re actively working to prevent future claims, which can make you a more attractive customer to insurers and help you secure a more favorable premium.
How to Choose the Right Policy
You’ve gathered the quotes, and now it’s time to make a decision. While it’s tempting to just pick the one with the lowest price, choosing the right policy is about finding a reliable partner who will be there for you when it matters most. This final step is about securing real peace of mind, not just a piece of paper. Let’s walk through how to compare your options thoughtfully and select the best coverage for your home.
Do a Final Background Check on the Insurer
A policy is only as good as the company that backs it. Before you commit, spend some time looking into the insurer's track record. You want a company that not only offers a fair price but also pays claims efficiently and treats its customers well. A great place to start is by checking their financial strength rating from independent agencies like AM Best. Think of it as a credit score for insurers; a rating of "B" or higher suggests they have the financial stability to pay out claims, even after a major disaster. Also, read customer reviews to get a feel for their service. A little research now can save you a massive headache later.
How to Check an Insurer's Financial Strength Rating
Think of an insurer's financial strength rating as its credit score. It’s a straightforward grade that tells you whether the company has the financial muscle to pay out claims, even after a widespread disaster. This isn't just a nice-to-know detail; for homeowners in high-risk areas, it's essential. You can easily look up any insurer’s rating through independent agencies like AM Best. You’re looking for a rating of "B" or higher, which signals that the company is on solid financial footing. This simple check gives you confidence that the partner you choose won't just be there to collect your premium but will have the resources to help you rebuild when you need it most.
Read the Fine Print (Really)
I know, I know—no one enjoys reading dense insurance documents. But this is one time when you absolutely have to read the fine print. Every policy has exclusions (what it doesn't cover) and limitations (the maximum amount it will pay for a specific loss). For homeowners in high-risk areas, you need to be crystal clear on these details. Does the policy have specific exclusions related to wildfires or mudslides? Are there limits on coverage for detached structures like a shed or guest house? Understanding these details upfront ensures there are no devastating surprises if you ever need to file a claim.
Double-Check Your Coverage Before You Sign
When comparing quotes, make sure you’re looking at policies that offer similar levels of protection. A cheaper quote might mean you’re getting less coverage for your dwelling, personal property, or liability. Double-check that the dwelling coverage is enough to completely rebuild your home at current construction costs—not just its market value. It’s also smart to ask about adding an "inflation guard" endorsement, which automatically adjusts your coverage limits to keep up with rising costs. This small feature can make a huge difference in ensuring you’re never underinsured.
How to Officially Start Your New Policy
Once you’ve chosen the best policy, it’s time to make it official. You’ll need to complete the final application, sign the necessary documents, and make your first premium payment. Be sure to provide the most accurate and up-to-date information about your home to lock in your quote. One final, crucial step: don’t cancel your old policy until you have written confirmation that your new one is active. You never want to risk even a single day without coverage. With your new policy in hand, you can finally relax, knowing your home is properly protected.
Related Articles
- Western US Home Insurance | Wildfire & High-Risk Coverage | Five Bays Insurance Agency
- Policy Checkup for High-Risk Homeowners | Five Bays Insurance Agency
- FAQ: Wildfire & High-Risk Home Insurance | Five Bays Insurance Agency
- Disclaimers & Disclosures | Five Bays Insurance Agency
- Five Bays Insurance Agency Home
Frequently Asked Questions
I've been dropped by my insurer. What's my first step? First, take a deep breath. Getting a non-renewal notice is stressful, but it's a problem you can solve. Your first move shouldn't be to panic-call the first company you see on a billboard. Instead, use this as an opportunity to get organized. Gather your current policy documents and make a detailed list of your home’s features and any recent upgrades. Then, your very next step should be to contact an independent insurance agent who specializes in high-risk properties. They have the expertise and carrier access to do the heavy lifting for you.
Will making my home safer with things like defensible space actually lower my premium? Yes, it absolutely can, but it's important to see it as part of a bigger picture. Insurers want to see that you are actively working to reduce your property's risk. Creating defensible space, installing a fire-rated roof, or adding ember-proof vents are powerful signals that you're a proactive homeowner. While these actions won't magically cut your premium in half overnight, they can make the difference between getting an affordable quote and getting no quote at all. Be sure to document every improvement with photos and receipts to build the strongest case for your home.
Is the California FAIR Plan a good long-term solution? Think of the FAIR Plan as a critical safety net, not a permanent solution. It provides essential, last-resort fire coverage when you can't find it on the private market, ensuring your home's structure is protected. However, it's a basic policy and doesn't include common protections like liability or theft coverage. To get that, you'll need to buy a separate "Difference in Conditions" policy. While it's a workable option, the goal should always be to improve your home's risk profile enough to qualify for a more comprehensive and often more affordable policy from a private insurer.
My quote seems too high. Is the price negotiable? While you can't haggle over an insurance premium the way you might a car price, you can absolutely influence the final number. If a quote comes in high, have a direct conversation with the agent. Ask them to walk you through the factors driving the cost. You may be able to adjust your deductible to lower the premium. This is also your chance to make sure they haven't missed any key details, like a recently installed security system or a brand-new roof, that could qualify you for discounts.
Why is working with an independent agent so important for a high-risk home? An independent agent is your single greatest advantage in a tough market. Unlike a captive agent who only works for one company, an independent agent partners with multiple insurers, including specialty carriers that focus on high-risk homes. They can shop your application around to find the best possible fit, saving you the time and frustration of applying to company after company. They understand the specific requirements of different carriers and can help you present your home in the most favorable way.


